
Most people think of Know Your Customer (KYC) as that annoying step where you upload your passport and take a selfie to open a bank account. It feels like friction. But for financial institutions and blockchain projects, KYC compliance is quietly becoming one of the biggest competitive advantages in the industry. It’s not just about ticking boxes for regulators anymore; it’s about building trust, cutting fraud costs, and actually making it easier for real customers to join.
The landscape has shifted dramatically since the USA PATRIOT Act of 2001 mandated these checks. Today, with global KYC spending hitting $14.3 billion in 2023, the focus has moved from simple document checking to intelligent risk management. If you’re running a regulated business or a crypto platform, understanding the real benefits of KYC can change how you view your compliance stack. Let’s break down why this process is worth more than just avoiding fines.
Turning Regulatory Burden into Trust
Here’s a counterintuitive fact: rigorous security makes customers feel safer, not more annoyed. According to a 2024 survey, 83% of customers reported greater confidence in financial institutions that demonstrate strong security protocols. When users see that a platform takes identity verification seriously, they assume their funds are safe. This is crucial in the blockchain space, where "not your keys, not your coins" is a common mantra, but centralized exchanges still hold billions in assets.
Think about it this way. If you were depositing $50,000 into a new DeFi platform, would you prefer one that lets anyone sign up with an email address, or one that verifies identity? The latter signals stability. SWIFT’s research backs this up, showing that KYC compliance is the backbone of successful risk management programs. Institutions with advanced KYC systems experienced 58% fewer regulatory citations. That means less legal headache and more reputation capital.
Cutting Fraud and Risk Exposure
Fraud isn’t just an inconvenience; it’s a massive cost center. Identity fraud incidents dropped by 67% among financial institutions that implemented robust KYC procedures, according to Shufti Pro’s analysis of 127 firms. In the world of cryptocurrency, where transactions are often irreversible, catching a scammer before they move money is everything.
Enhanced Due Diligence (EDD) plays a huge role here. For high-risk customers, like those from jurisdictions flagged by the Financial Action Task Force (FATF), extra layers of verification kick in. Northrow’s case studies show that banks using comprehensive Customer Due Diligence (CDD) protocols saw a 43% reduction in fraudulent account openings. This isn’t just about stopping money laundering; it’s about protecting your balance sheet from bad actors who might exploit loopholes.
- Identity Fraud Reduction: 67% drop in incidents with proper KYC.
- Fraudulent Accounts: 43% decrease with enhanced due diligence.
- Regulatory Fines: Global AML fines hit $4.2 billion in 2023, a 17% increase year-over-year.
Improving Customer Experience Through Automation
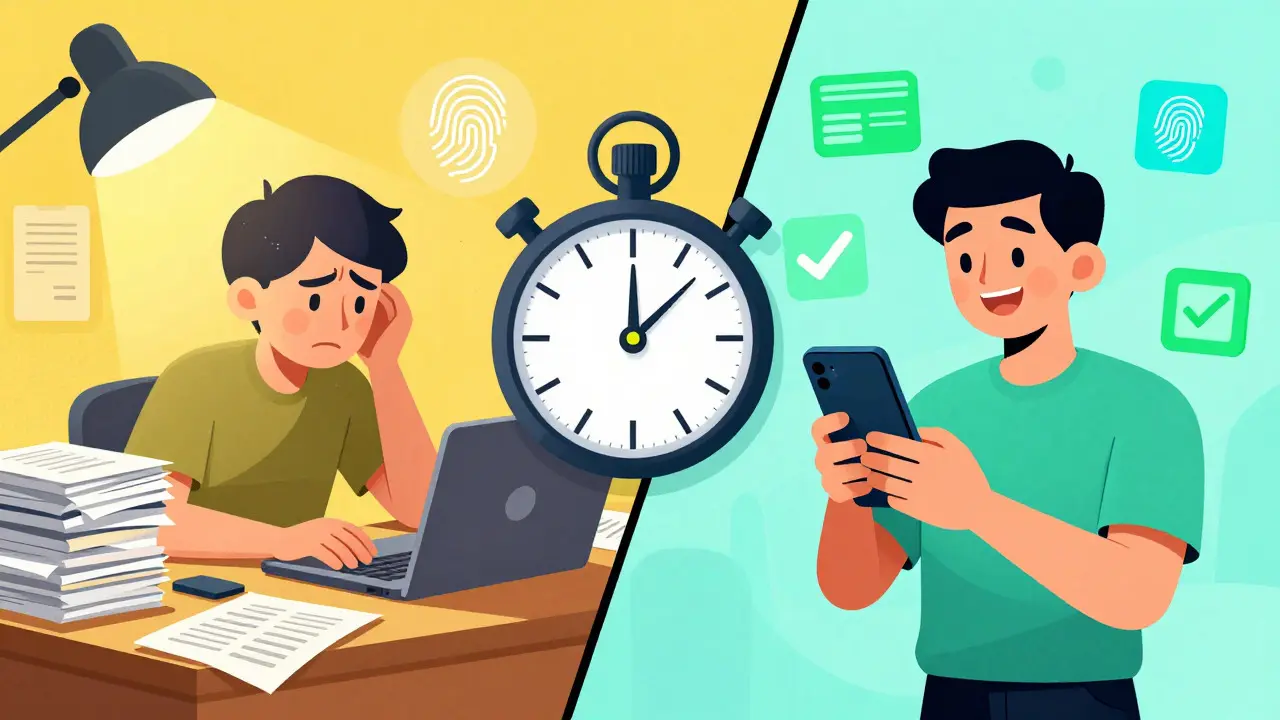
Let’s address the elephant in the room: speed. Traditional KYC could take 3-5 days. Modern systems aim for minutes. Gartner’s 2024 analysis reveals that financial institutions with high KYC maturity scores report 41% higher customer satisfaction. How? By removing friction.
Technologies like Optical Character Recognition (OCR) and biometric matching now process documents with over 98% accuracy. Facial recognition matching rates have hit 99.8% according to recent benchmarks. When a user can verify their identity in under 8 minutes, they stay. A Forrester study found that 31% of customers abandon applications if the process drags on longer than that. So, fast KYC isn’t just good for compliance teams; it’s good for conversion rates.
JPMorgan Chase offers a great example. Their 2022 modernization effort reduced false positives by 53% by integrating AI incrementally rather than replacing their entire system overnight. This approach kept disruption low while improving accuracy. It proves that you don’t need to rip out your old infrastructure to get better results.
Cost Efficiency and Operational Savings
Many leaders assume compliance is purely a cost center. The data says otherwise. Thomson Reuters Legal found that 78% of institutions that optimized their KYC processes saw improved customer acquisition rates within 18 months. How does saving time on paperwork lead to more customers? Because sales teams spend less time chasing missing documents and more time closing deals.
Automation also slashes manual processing costs. Optimized KYC processes can reduce manual labor expenses by 35%. For community banks, which often spend 23% more on compliance per customer than larger institutions due to less sophisticated tools, this efficiency gain is critical. As the European Union’s 6th AML Directive expands requirements to include cryptocurrency exchanges, smaller players need every advantage they can get to compete with giants like Refinitiv or Persona.
| Metric | Traditional Manual KYC | Automated/Digital KYC |
|---|---|---|
| Average Onboarding Time | 3-5 Business Days | < 8 Minutes (Instant) |
| Document Processing Accuracy | Variable (Human Error) | 98.5%+ (OCR/AI) |
| False Positive Rate | High | Reduced by up to 53% |
| Customer Abandonment Risk | High (>31% if slow) | Low (Seamless Flow) |
| Scalability | Linear (More staff needed) | Exponential (Cloud-based) |
Navigating the Blockchain Specifics
In the crypto world, KYC used to be controversial. Purists argued it killed decentralization. But the reality is shifting. With the EU’s MiCA regulation and other global frameworks, Virtual Asset Service Providers (VASPs) are now required to verify users. This creates a level playing field.
For blockchain projects, KYC acts as a filter. It separates serious investors from wash traders and bots. While it may seem restrictive, it opens doors to institutional capital. Banks are hesitant to partner with anonymous entities. By implementing KYC, you signal that your project is ready for mainstream finance. The SWIFT KYC Registry, used by nearly 6,000 financial institutions, is even expanding to include corporate customers, standardizing how businesses verify each other globally.
Moreover, blockchain technology itself is helping KYC. Self-sovereign identities (SSI) allow users to prove specific attributes (like age or residency) without revealing their entire life history. This privacy-preserving approach aligns with Web3 values while satisfying regulators. It’s a win-win that pure manual compliance never achieved.
Future-Proofing Your Compliance Strategy
Where is this all heading? The FATF’s 2024-2026 action plan aims to harmonize KYC requirements across jurisdictions. This could cut compliance costs by 27% for multinational institutions. Right now, dealing with different rules in the US, EU, and APAC is a nightmare. Standardization will simplify that significantly.
Biometrics are also going mainstream. Gartner predicts that by 2026, 85% of new account openings will use biometric verification, up from 47% in 2023. If you’re still relying solely on PDF uploads, you’re falling behind. Real-time monitoring is another key trend. The Basel Committee guidelines now push for continuous transaction analysis rather than periodic reviews. 68% of major institutions are already moving in this direction.
The bottom line? Treat KYC as a strategic differentiator. McKinsey notes that institutions viewing KYC this way achieve 19% higher customer lifetime value. It’s no longer just about surviving audits; it’s about winning customers who value security and speed.
Frequently Asked Questions
Does KYC kill blockchain decentralization?
Not necessarily. While traditional KYC requires central points of verification, emerging technologies like self-sovereign identities (SSI) allow users to control their data. This maintains user autonomy while meeting regulatory needs. Many large-scale blockchain projects now use hybrid models that satisfy both communities.
How long should a digital KYC process take?
Ideally, under 8 minutes. Research shows that if the process exceeds this timeframe, 31% of users may abandon their application. Leading platforms aim for instant verification using biometrics and OCR, reducing wait times from days to seconds.
What is the difference between CDD and EDD?
Customer Due Diligence (CDD) is the standard verification for most users, involving basic ID checks. Enhanced Due Diligence (EDD) applies to high-risk customers, such as Politically Exposed Persons (PEPs) or those from high-risk jurisdictions. EDD involves deeper background checks and ongoing monitoring.
Is KYC mandatory for all crypto exchanges?
In most major jurisdictions, yes. Regulations like the EU’s MiCA and the US Bank Secrecy Act require Virtual Asset Service Providers (VASPs) to perform KYC. While some decentralized protocols remain permissionless, any exchange acting as a gateway for fiat-to-crypto conversion typically must comply.
How does AI improve KYC accuracy?
AI reduces human error and speeds up processing. Machine learning algorithms can detect forged documents, match faces against watchlists in real-time, and analyze transaction patterns for anomalies. This leads to lower false positive rates and faster approvals for legitimate users.

Comments
Rachel Etheridge
Oh my gosh, finally someone is saying what we all have been screaming about for years!! I am literally shaking with excitement because this is so true. We need to stop treating KYC like it is a punishment and start seeing it as a shield. It makes me feel so much safer knowing that the people on these platforms are actually real humans and not just bots stealing our money. The fact that fraud dropped by 67% is absolutely amazing and gives me so much hope for the future of finance. I used to hate uploading my passport but now I see it as a small price to pay for peace of mind. Let us keep pushing for better systems because we deserve to feel secure in our digital lives.
Matt Reckdenwald
It really does change the vibe when you realize it's about trust rather than just red tape. I've seen too many friends get burned by sketchy DeFi projects that promised 'total freedom' but turned out to be rug pulls. When a platform takes the time to verify who you are, it feels like they respect your assets enough to protect them properly. It’s a subtle shift in mindset from 'getting over the hurdle' to 'joining a community that cares.'
Ashwin Bhandurge
Let's talk about the speed aspect! If you can verify in under 8 minutes, you win. I have personally watched customers abandon carts just because the onboarding took two days. In India, we value efficiency and clarity, and when a bank or app makes it seamless, loyalty follows. Don't underestimate the power of a smooth user journey; it is the ultimate motivator for growth.
Nadia Christian
Great point! And let's not forget that strong security keeps the bad actors out. Our country has some of the best regulatory frameworks in the world, and it shows in how stable our financial institutions are compared to those chaotic offshore zones. It is essential that we maintain high standards to protect American jobs and investments. ! ! !
jeffry jones
Agreed. From an ops perspective, reducing false positives is key. JPMorgan's approach was smart. Incremental AI integration beats big-bang replacements. Less friction, higher conversion. Simple math.
Martha Packard
You're all missing the bigger picture here. This isn't about 'trust,' it's about control. Every time you hand over your ID, you're handing over a piece of your sovereignty to a corporate entity that will sell it to the highest bidder. The 'safety' argument is just a shiny object to distract you from the fact that you are now permanently tracked. Real freedom means no one knows who you are until you decide to show them. Until then, you're just a data point in their database. Wake up.
Ashwini Chaskar
Oh please spare us the privacy lectures, it's so exhausting to hear the same old recycled arguments every single time you clearly haven't read the full article because self-sovereign identities solve exactly that problem and yet here you are still complaining about things that don't even apply anymore honestly it's almost impressive how stubborn some people can be when presented with actual facts and working solutions but sure keep pretending the government is coming to take your passport while you sit in your living room wondering why your bank account got frozen for no reason at all
Jane yuan
The data supports the implementation. Standardization is inevitable. Embrace it.
Rebecca Springer
I think there is a lot of nuance here that gets lost in the debate. For smaller businesses, especially in emerging markets, the cost of compliance can be prohibitive without the right tools. But if we look at the EU's MiCA regulation, it creates a level playing field which is ultimately good for global trade. It forces everyone to play by similar rules, which reduces confusion and builds international trust. It's a slow process, but necessary for long-term stability.
J Shepherd
Spot on. Scalability is the main pain point for mid-sized firms. Cloud-based KYC stacks are becoming the norm now. Manual processes just don't scale linearly. You need exponential growth capabilities to compete with the big banks. The tech is ready, adoption is just catching up.
Alan Hawkins
Definitely. I work with a few fintech startups and they are all moving towards API-first verification models. It makes sense. Why hire more staff when software can do it faster and cheaper? The ROI is pretty clear once you look at the numbers. Most teams are realizing this now.
Steve Sulley
yeah but its all a con anyway... the whole system is rigged against the common man and they just use kyc to spy on us and freeze our accounts whenever they feel like it i mean look at how many times they have changed the rules already its all about control and profit for the elites down here in nigeria we know the struggle of dealing with unstable systems so we just laugh at their fancy new apps and biometrics its all just theater to make us feel safe while they drain our wallets slowly but surely lol